
Autumn Budget 2026: What did Chancellor Healey announce for the housing market?
Chancellor John Healey has delivered his first Autumn Budget - and here is what the fiscal update means for the housing market.
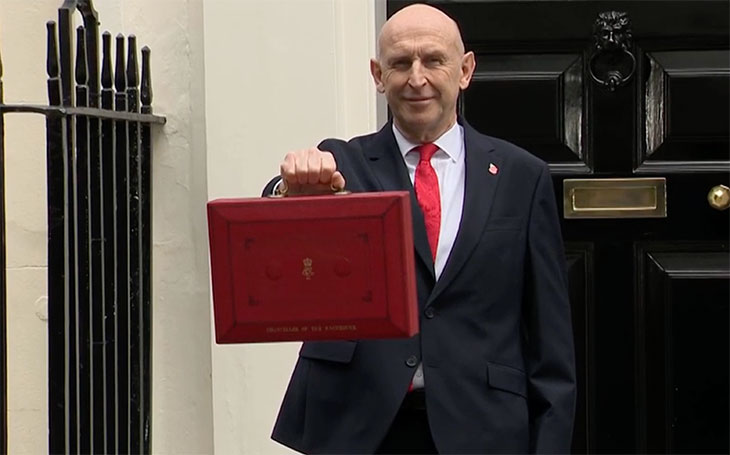
Landlords will face higher taxes on rental income and first-time buyers will have to wait until Spring 2027 for the Government’s latest housing support scheme, the Chancellor has confirmed.
John Healey delivered his first Autumn Budget today, dashing any hopes for Stamp Duty cuts or reforms.
There was no major rabbit out of the hat, but there are a few changes that could affect the housing market and estate, lettings agents and landlords.
Tax on rental income
Landlords were already expecting higher taxes on rental income from April 2027, with previous Chancellor Rachel Reeves announcing that rates would rise by two percentage points.
But Healey confirmed in his speech that the income tax on rent will be hiked by a further two percentage points, meaning landlords will pay tax rates of 24%, 44% and 49% depending on their tax band from April 2027.
Heather Powell, a Partner at accountants Blick Rothenberg, says: “An extra 2% on rental income really is the final nail in the coffin for private investors in rental properties – tax rates of 24%, 44% and 49% – and a deduction for interest that is restricted to the basic rate will mean that landlords will be looking to sell up and invest their money elsewhere.
“Tenants looking for good homes to rent will find reduced supply, and thus higher rents due to competition, and will be driven into the arms of corporate build to rent investors.”
Your First Home
Healey confirmed that the Your First Home scheme will launch in Spring 2027.
It will help first-time buyers by supporting a 2.5% deposit with a Government equity loan to purchase a new-build.
The Treasury is providing £4.7billion of funding.
Income caps will be set at £110,000 per household outside London and £140,000 inside London. Price caps will be set based on local authority median prices to ensure support is targeted at those who need it, with inner and outer London caps of £650,000 and £500,000 respectively.
Richard Donnell, Executive Director of Zoopla, says: “The Budget has delivered a welcome boost for first-time buyers and the home-building industry. Localised price caps set at what first-time buyers want to pay for new homes means the Your First Home scheme will have around half the impact of the old Help to Buy scheme.
“If local price caps are set at what first-time buyers want to pay for new homes, Zoopla estimates that over a third of new homes will be eligible for the Your First Home scheme with up to 30,000, or one in ten, first-time buyers set to benefit each year.
“This will cost the Government around £1.5billion a year so looks set to run for three years based on the £4.7billion announced in the Budget. The income caps announced in the Budget are high enough to ensure all these homes are affordable with a 2.5% deposit assuming a 4.5x loan to income mortgage.
“When the scheme was announced before the party conferences Zoopla saw an immediate 40% jump in searches for new homes at the prospect of support with an equity loan to buy new homes. The appetite for the scheme is there, but its success will depend on getting the price caps right to ensure enough homes qualify to make a meaningful difference.”
James Nightingall, founder of property search service HomeFinder AI, adds: “The Your First Home scheme looks promising on paper and while it might not be the best solution for everyone, it will undoubtedly enable and motivate first time buyers to get on the property ladder. This is also good news for developers as the new-build sector was in dire need of an initiative that gets the market moving again.”
Mansion Tax
The Government confirmed plans to go ahead with the High Value Council Tax Surcharge on homes worth £2million and above.
The first bills will land in March 2028.
The Government said it will introduce a deferral scheme, a series of discounts and exemptions and a 100% premium on properties left empty and unoccupied for 12 months or more.
First Time Buyer ISA
A new First Time Buyer ISA will be released in April 2029. The product will retain the generosity of the Lifetime ISA, allowing contributions of up to £4,000 a year with a 25% Government bonus.
The bonus will be paid on the value of the account balance when funds are withdrawn for a qualifying first home purchase, up to the value of £450,000, so avoiding the need for any withdrawal charge. The new product will have no upper age restriction.
In recognition that some Lifetime ISA holders may wish to purchase a property above the current £450,000 property price cap, the Budget document reveals that from October 29th 2026, there will be a reduced withdrawal charge of 20%, while the value of individual contributions will be protected.
 Iain McKenzie, Chief Executive of The Guild of Property Professionals, says: “The property market needs confidence and consistency, and our hope is that this Autumn Budget will provide a clearer direction for buyers, sellers and the wider housing sector.
“With borrowing costs, inflation and the cost of living continuing to influence household decisions, sentiment will be just as important as the individual measures announced today.
“Any initiative that makes home ownership more accessible should be welcomed, and Your First Home has the potential to help aspiring buyers who are struggling to build a deposit. A new First Buyer ISA could also offer a further incentive to save towards a first home. But these schemes must translate into meaningful, sustainable progress for buyers, rather than simply bringing forward demand without addressing the wider affordability challenge.
“First-time buyers in particular need to understand the long-term financial implications of the support available, including any repayment obligations once an interest-free period ends. Access to independent financial advice will be crucial in helping them make informed decisions.
“Ultimately, the market will benefit most from measures that support genuine affordability and restore confidence. Mortgage rates have been creeping up ahead of the Budget, so we will be watching closely to see whether the economic uncertainty surrounding the announcements begins to ease. A more stable outlook would give buyers and sellers the confidence to make their next move.”

Your first home scheme has not learnt the lessons from help to buy scheme, all this did was make developers millions by selling over inflated units, the scheme should be spread across the market to really give the market a push. All this is doing is pushing buyers to new builds which are over priced in the first place.
So a great help for house builders to get their asking price with taxpayer cash and a huge mortgage for the first timers. Not much option really as the tide of the PRS goes out even further leaving renters flapping around in the shallows.
Everyone pays the same tax rate on a given level of income . . . . except for landlords, of course. They are now officially-designated punchbags to self-righteous Progressives, who are always keen to find an outlet for the essential division and hate that their ideology demands, where they can posture as liberators of the oppressed, slayers of the oppressors.
So landlords uniquely have three extra hate taxes imposed on them, while everyone else pays the standard tax rate for their income. There is Section 24, Reeves’s 2% and now Healey’s 2% hate tax.
Landlords, in my experience, double the occupation rate of the housing stock. The government thinks we need less housing?